

The U.S. condominium financing landscape just underwent its most significant regulatory change in over a decade. Effective August 3, 2026, Fannie Mae and Freddie Mac eliminated the Limited Review and Streamlined Review options for condominium projects, requiring all financed purchases to go through a Full Review process. This shift has profound implications for buyers, sellers, and investors across Miami and South Florida.
What Changed — and Why It Matters
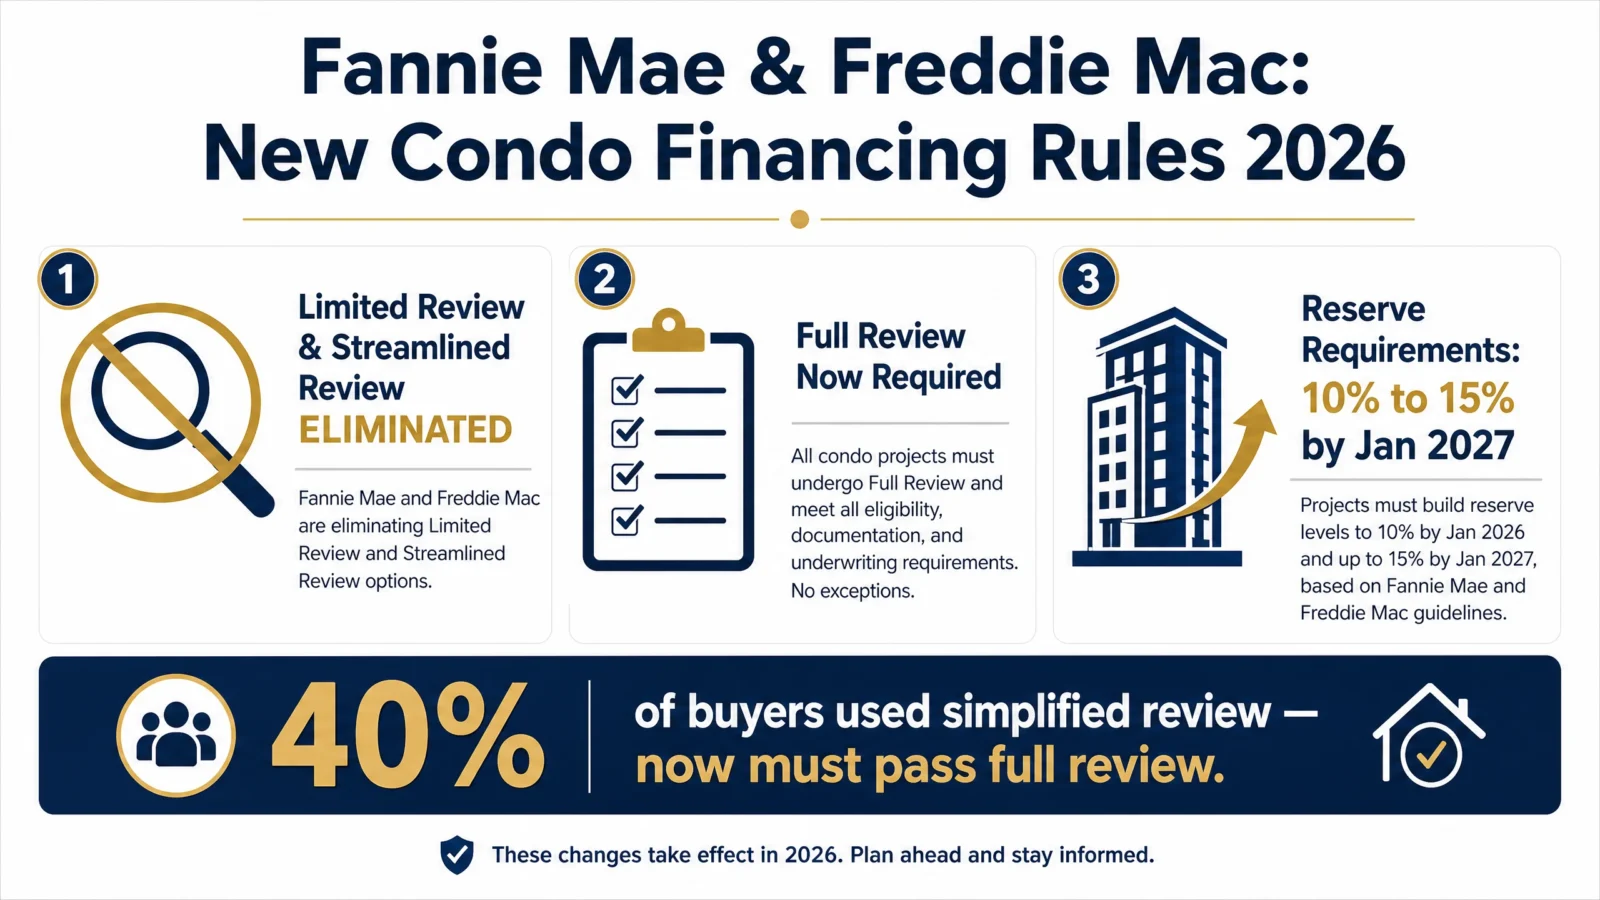
For years, the Limited Review (Fannie Mae) and Streamlined Review (Freddie Mac) allowed buyers to finance condominium purchases with minimal scrutiny of the building’s financial health. These simplified processes covered approximately 40% of all condo purchases with conventional financing. Under the new rules, every condo project must undergo a comprehensive Full Review that evaluates the association’s finances, reserve funds, insurance coverage, and structural maintenance plans.
The change stems from lessons learned after the Surfside collapse in 2021 and the subsequent Florida Senate Bill 4-D, which mandated structural inspections and reserve studies for all condo buildings. Now, the federal mortgage giants have aligned their underwriting standards with these safety requirements.
Reserve Requirements Are Rising
The most impactful change for condominium associations is the timeline for reserve fund requirements. By January 1, 2027, condo projects must demonstrate reserves equal to at least 15% of their annual budget — up from the previous 10% threshold. The “baseline funding method,” which allowed buildings to operate with reserves near zero, will no longer be accepted.
For buyers, this means condominium associations that have been neglecting their reserve funds will face increased difficulty in securing financing approval. Buildings that fail the Full Review may be outright denied for conventional mortgages, forcing buyers to seek expensive portfolio loans or pay cash.
What This Means for Miami Buyers
Miami’s condominium market is uniquely positioned to feel this change. The city has one of the highest concentrations of condo living in the United States, with thousands of buildings ranging from pre-1980 constructions to brand-new towers. Older buildings that have not proactively funded their reserves will face the most pressure.
For cash buyers, the change represents a significant competitive advantage. Without financing contingencies, cash purchases close faster and carry no risk of a building-level denial. In a market where 50%+ of luxury transactions are already cash, this regulatory shift further incentivizes all-cash strategies.
How to Navigate the New Rules
Whether you’re buying a condo in Brickell, Downtown Miami, or Sunny Isles, here’s what to consider in the post-2026 landscape:
For buyers with financing: Request the association’s financial documents, reserve study, and insurance certificates before making an offer. Buildings with strong reserves and recent structural inspections will pass the Full Review quickly. Buildings with deferred maintenance or underfunded reserves may not qualify at all.
For condo owners and investors: Ensure your building’s association is proactively funding reserves. Buildings that fail the Full Review lose their entire pool of conventional-financed buyers, which can suppress property values.
For cash buyers: You now have even greater negotiating leverage. Sellers in buildings with weak financials will increasingly need cash buyers to close transactions.
Key data: Limited/Streamlined Review eliminated Aug 3, 2026 | Full Review now required for all financed purchases | Reserves rising from 10% to 15% by Jan 1, 2027 | ~40% of financed condo purchases previously used simplified review.
The Faccin Perspective
At Faccin Investments, we’ve been advising clients on the implications of Florida’s condo reform since 2021. The elimination of simplified financing review adds another layer of due diligence to every condo purchase. Our team evaluates each building’s financial health, reserve adequacy, and structural compliance before recommending any property to our clients — ensuring that your investment is not only beautiful but also financially sound.
Ready to explore Miami’s condominium market with confidence? Contact Faccin Investments for expert guidance on navigating the new financing landscape.