

Miami’s luxury real estate market is frequently discussed as a single entity, but the data tells a more nuanced story. In Q1 2026, four of the city’s most sought-after neighborhoods — Brickell, Coconut Grove, South Beach, and Coral Gables — are operating under fundamentally different supply and demand conditions. For buyers and investors evaluating where to place capital in 2026, understanding these distinctions is not optional. It is the foundation of a sound acquisition strategy.
Across Miami-Dade’s luxury tier, the dominant theme is compressed inventory in high-demand urban corridors paired with softer absorption in historically prestige-driven coastal markets. Total $1M+ closings reached 847 transactions in Q1 2026, with average days on market falling from 61 days in Q1 2025 to 48 days in Q1 2026. Cash transactions represented approximately 58% of luxury closings — a figure that underscores the market’s independence from mortgage rate fluctuations that have constrained activity in most U.S. housing markets.
Brickell: The Dominant Driver
Brickell recorded 215 luxury closings in Q1 2026, the highest of any Miami submarket, at a median price of $1,180 per square foot. With only 312 active listings and 3.2 months of supply, Brickell is firmly in seller’s market territory. Sellers in top-tier buildings are frequently receiving full-ask or above-ask offers within the first two weeks of listing, and the sub-40-day average days on market confirms this is a decision market, not a browse market.
The demand drivers are structural. Brickell has evolved from a financial district into a full-service urban hub, attracting technology entrepreneurs, hedge fund executives, and venture capital investors relocating from California and other high-tax states. Ken Griffin’s Citadel is currently constructing a 1.7 million-square-foot tower in Brickell, and Peter Thiel recently set a Miami record by leasing space at 830 Brickell for approximately $250 per square foot. Miami now holds the highest average office rent among 50 U.S. cities, surpassing New York City and the Bay Area — a signal that the corporate migration fueling residential demand is not a temporary trend.
Coconut Grove: The Outperformer Nobody Expected
Coconut Grove is running 2.8 months of supply — the tightest of any luxury submarket in this analysis — with 148 closings in Q1 2026 at a median of $820 per square foot. With only 196 active luxury listings, the Grove is the most inventory-constrained neighborhood in this comparison. Properties in the $1.2M–$2.5M range are particularly active, and the 44-day average days on market reflects consistent, organic demand rather than speculative activity.
South Beach: More Inventory, More Leverage
South Beach remains the most recognizable name in Miami luxury real estate, and at 162 Q1 closings and a median of $1,045 per square foot, it is far from dormant. However, with 487 active luxury listings, 5.1 months of supply, and an average of 67 days on market, South Beach is the softest of the four neighborhoods tracked here. Buyers have more time, more options, and more negotiating leverage than at any point in the past 30 months.
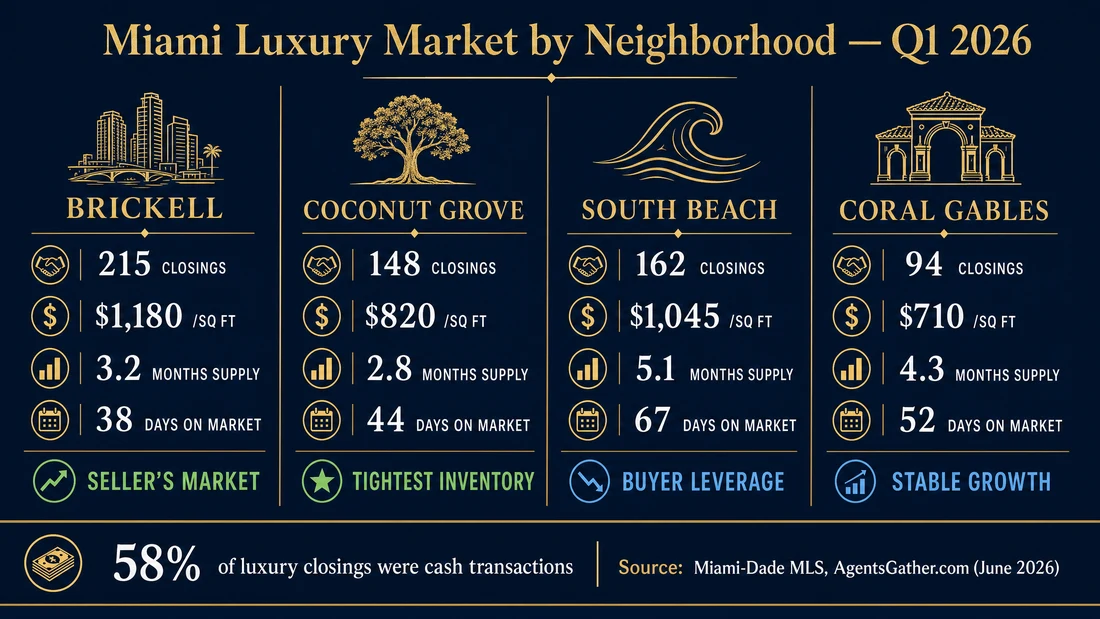
Key data: Q1 2026 luxury comparison — Brickell: $1,180/sq ft, 3.2 months supply; Coconut Grove: $820/sq ft, 2.8 months supply; South Beach: $1,045/sq ft, 5.1 months supply; Coral Gables: $710/sq ft, 4.3 months supply. Cash transactions: 58% of luxury closings. Source: Miami-Dade MLS (June 2026).
Coral Gables: Consistent, Deliberate, Priced for Patience
Coral Gables produced 94 luxury closings in Q1 2026 at a median of $710 per square foot — the lowest price per square foot in this comparison but also the most stable appreciation trajectory over the past three years. At 4.3 months of supply and 52 days on market, Coral Gables sits in balanced-to-slight-buyer-advantage territory.
What Buyers Need to Know Right Now
The 2026 Miami luxury market rewards preparation and specificity. Brickell and Coconut Grove demand speed and decisiveness — inventory is tight and well-priced properties move quickly. South Beach and Coral Gables offer more time and more negotiating room, but buyers who approach these markets without a clear strategy risk losing the best opportunities to more prepared competitors.
For buyers evaluating Miami luxury real estate in 2026, the right question is not whether to buy, but where — and at what price point the data supports a confident decision. To explore current listings across Brickell, Coconut Grove, South Beach, and Coral Gables, contact Faccin Investments for a personalized market consultation.
FAQ
Q: Which Miami neighborhood has the most inventory for luxury buyers in 2026?
A: South Beach has the most active luxury listings (487 units) and the longest average days on market (67 days), giving buyers the most options and negotiating leverage in Q1 2026.
Q: Is Brickell still a good investment in 2026?
A: Yes. With 215 luxury closings in Q1 2026, a median of $1,180 per square foot, and only 3.2 months of supply, Brickell remains the most active and supply-constrained luxury submarket in Miami.
Q: What is driving Coconut Grove’s luxury market in 2026?
A: Coconut Grove has the tightest inventory of any luxury submarket analyzed (2.8 months of supply), driven by limited new construction, strong organic demand from long-term buyers, and a preference for larger homes and lot sizes.